The figures and claims below come from a PANews article by Jae published on November 10, 2026, at 15:55 CST. They describe the market as of that report, not a later development.
A public correction to ultrasound money
On November 8, 2026, Ethereum co-founder Vitalik Buterin wrote on X that he would rather position ETH as a store of value than anchor it to the idea that burned fees support the price. PANews treated the post as a public revision of “ultrasound money,” the scarcity-through-burn story it called ETH’s most widely circulated narrative of the previous five years.
The tension the article described was already in the usage data. The network was handling more transactions and users were paying less, while Ethereum’s fee income—and the ETH destroyed with it—was shrinking. With gas destruction no longer working as the price ballast it had been sold as, PANews said an asset worth about $260 billion needed a different valuation anchor. Buterin’s stated answer was store-of-value status.
What the old math required, and what was actually burned
The older logic, as restated in the piece: users pay fees, the protocol burns ETH, and holders benefit indirectly if scarcity improves. The proposed replacement: Ethereum offers security, neutrality, and reliable financial infrastructure, so the ecosystem is willing to hold, stake, and use ETH for a long time.
Buterin’s own illustration, reported by PANews, was a discounting sketch rather than a forecast. If a token burned $1 billion of fees every year, a 4% discount rate would imply a theoretical present value of about $25 billion. The point he attached to it was that fees are not a stable cash flow, and that treating a peak as a permanent run-rate does not survive a cycle.
PANews ran the same 4% rate backward from the roughly $260 billion market value. On that arithmetic, supporting the capitalization would require about $10.4 billion of fees burned every year, continuously. The article said that amount was already far from conditions at the time.
The burn record in the piece:
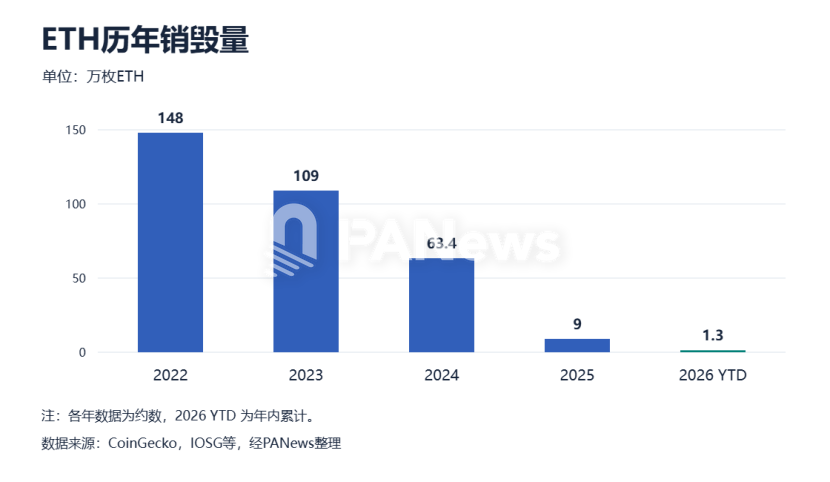
- About 1.48 million ETH was destroyed in 2022.
- About 13,000 ETH had been destroyed in 2026 up to the report, which PANews valued at roughly $27.3 million.
- By coin count, that is a drop of more than 99%. A section heading in the original described the decline as more than 90%; the count comparison in the body is the sharper figure.
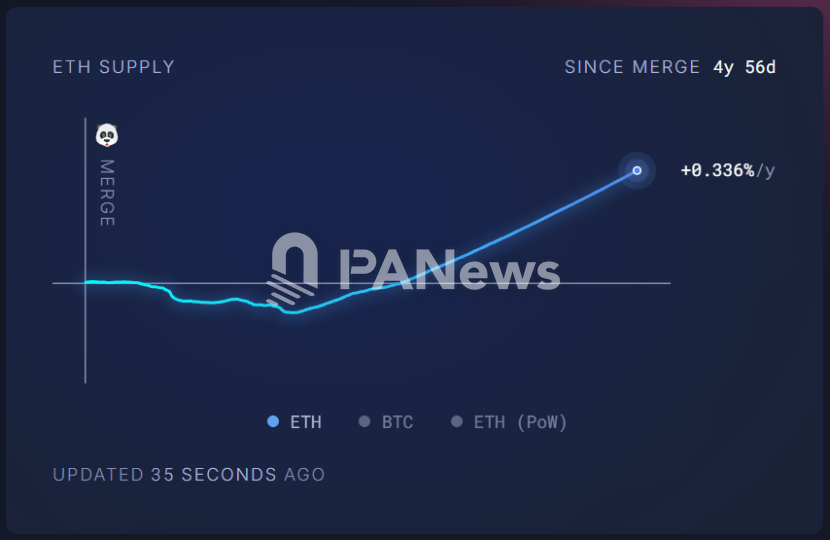
PANews also wrote that ETH had left net deflation and returned to net inflation in February of the previous year—February 2025, read from the article’s November 2026 dateline—and that the inflation rate had continued to rise. On that account, the deflationary promise tied to ultrasound money had already failed before the November 8 post.
Collateral and staking are documented; a new demand regime is not
The store-of-value version in the article is not “coins sit in a wallet.” PANews described ETH as base collateral: holders can stake it for rewards or post it in lending markets such as Aave for liquidity, and related staked positions can move into other DeFi uses.
Bitmine chairman Tom Lee was cited as agreeing that ETH is not a cash-flow token on the model of HYPE or LIT, but pure, trusted collateral. That is his characterization. The article did not present a measured cash-flow comparison that would establish it.
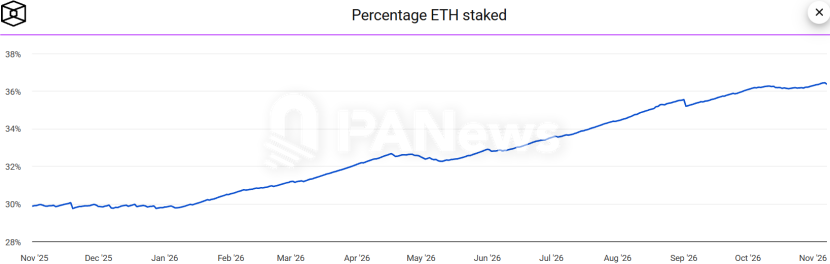
The demand PANews called most direct is staking. Citing The Block, it said staked ETH was 36.36% of circulating supply at the time of the report, against 29.91% a year earlier. A large share of supply locked in validators is not the same thing as short-term trading inventory, and the article read it as supply performing a security function. The staking ratio does not, by itself, show that new buyers are accumulating ETH because they treat it as money.
Large on-chain stocks are not net buying of ETH
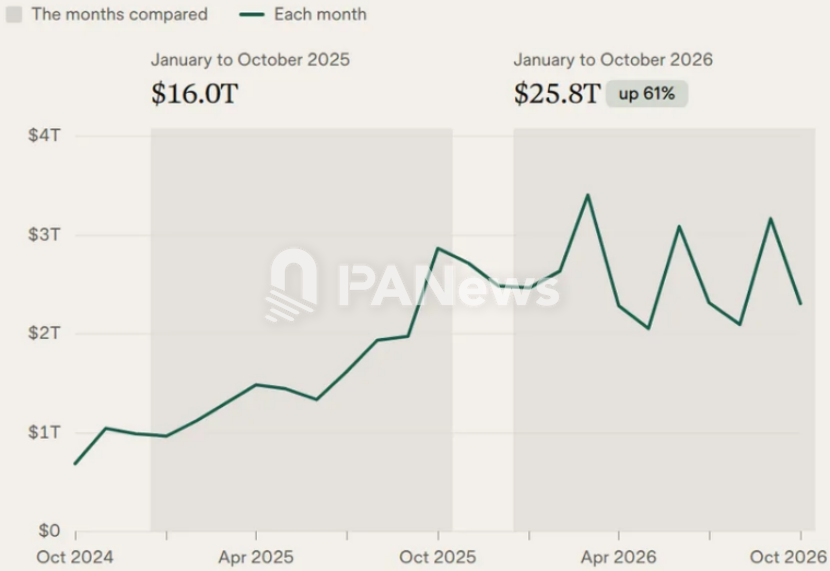
Citing Ethereum Institutional, PANews said Ethereum mainnet stablecoin transfers totaled $25.8 trillion in the first ten months of 2026, up 61% year over year.
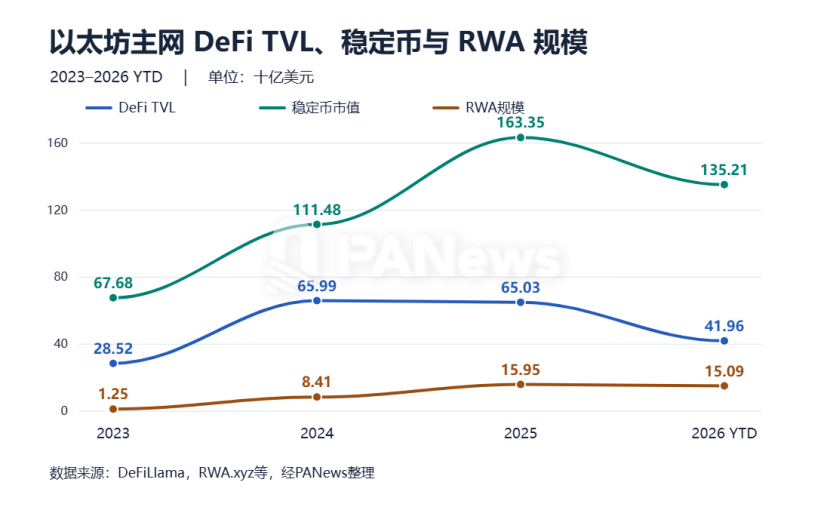
DeFiLlama figures placed beside that result: mainnet DeFi total value locked around $42 billion, stablecoin market value above $135 billion, and real-world-asset scale of $15 billion.
Those measure activity and asset stocks. The article’s example of why they need not become ETH demand was hypothetical, not a named deal: an institution could issue $1 billion of tokenized Treasuries on Ethereum, with real Treasuries as collateral, coupon income as the yield, and USDC for settlement, while spending only a small amount of ETH on gas. A larger pool of assets using the chain does not demonstrate net purchases of ETH.
That is the test PANews set. Store-of-value status is not created by declaring it. ETH would have to be base capital that on-chain finance must hold, rather than fuel bought only when someone needs gas. The November 2026 article stated that requirement. It did not present evidence that this demand shift had already happened.
Fee value was already leaving the base layer
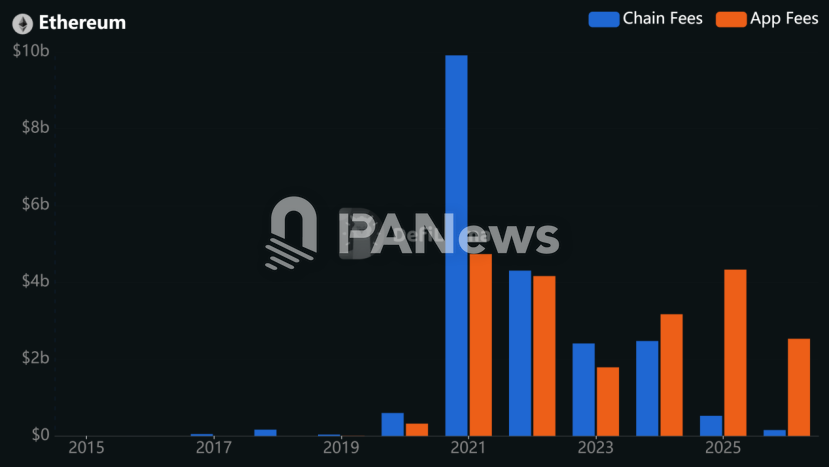
The piece argued that the break was visible in the burn collapse, and that fee income inside the ecosystem had been moving toward layer 2 and applications. It compared the ecosystem to a business whose base-layer revenue was being diverted.
Citing DeFiLlama, PANews said fees generated by the Ethereum chain were overtaken by application-layer fees on mainnet as early as 2024. For 2026 up to the report, it put mainnet fees at about $152 million and application-layer fees at about $2.529 billion, more than 16 times the mainnet total.
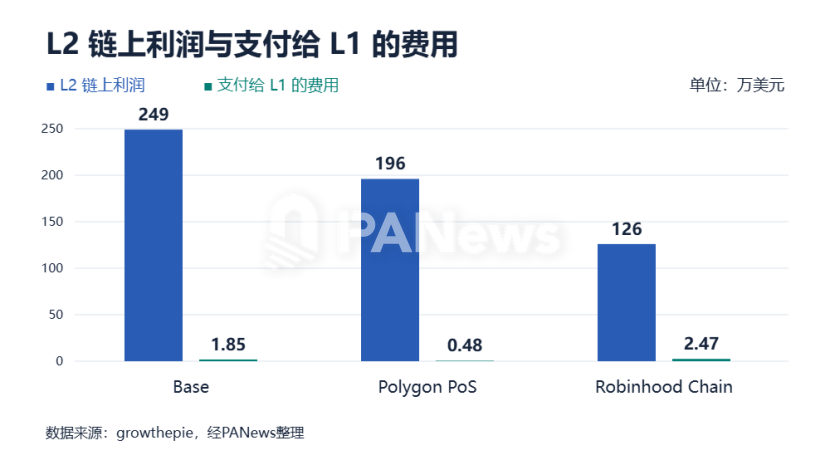
Layer 2 was the worked case, with Base as the example. Base uses Ethereum for settlement and security, keeps its own execution environment and user entry point, charges end users, and pays Ethereum for data publication and settlement. The spread is its on-chain gross profit.
Citing growthepie for the 30 days before the article:
- On-chain profit across the top three Ethereum L2s was about $5.71 million, of which Base contributed about $2.49 million.
- Settlement fees those L2s paid to Ethereum mainnet totaled about $48,000.
- Base paid $18,500, which the article said was lower than Robinhood Chain’s payment. Robinhood Chain’s amount was not stated.
On those figures, most fee value stayed with the L2s. It did not reach Ethereum mainnet and was not income for ETH holders.
A further concern in the piece is about brand, not about a measured fee or security loss: if more users do all of their activity on Base, Arbitrum, and other L2s and rarely touch Ethereum, the service they recognize belongs to the L2 or the front end. That remains an inference about attention.
Cheaper fees open uses; they do not prove a valuation
PANews noted that lower fees are what scaling is for. When a transfer cost several dollars, many high-frequency or small-value uses were uneconomic. At a few cents or less, high-frequency payments by AI agents, micro-transactions, and automated strategies become possible in principle. Whether that activity grows enough for volume to offset the lower fee per transaction was left explicitly unverified.
Lee’s additional claim—that a store-of-value framing will let ETH capture value in a coming tokenization and “AI supercycle”—is a forward-looking assertion. The article reported it. It did not supply a mechanism, a quantity of ETH demand, or a result that can be checked against the fee and burn figures above.
What is shown, and what is only a change of story
As of the November 10, 2026 report, the documented gap is between the ultrasound-money promise and the burn record: destruction down by more than 99% versus 2022 on a coin-count basis, net inflation already restored, and a fee run-rate far below the roughly $10.4 billion a year implied by PANews’s 4% illustration for a market value near $260 billion. Separately, the DeFiLlama and growthepie figures show application and rollup layers retaining far more fee value than they pass to Ethereum.
The store-of-value alternative changes the claim. Staking at 36.36% of supply, and the reported stablecoin, DeFi, and RWA stocks, show that Ethereum is used and that a large share of ETH is locked. They do not show that usage forces ongoing net purchases of ETH—the demand the new story needs, and that the old burn story no longer supplies.
Original article: Jae, PANews, November 10, 2026, 15:55 CST. PANews.